INVESTMENT ILLUSTRATION 03
Is Spain's Urban Self-Storage Market
Ready for a Consolidation Platform?
A catchment-level investment assessment that separates market growth from property and occupancy risk.
EUR 52m
CAPITAL ENVELOPE
5 metros
INITIAL GEOGRAPHY
4 years
BUILD PERIOD
Acquire + convert
CAPITAL ROUTE
INVESTMENT QUESTION Should a real estate investor assemble an operating platform through selected acquisitions and conversions in Madrid, Barcelona, Valencia, Malaga and Seville?
National growth can coexist with weak local economics. The decision turns on facility-level occupancy, achieved rent, conversion cost, competitive supply and the availability of assets that can be integrated into one operating model.
MICRO-MARKET DIAGNOSIS
The investable market is a set of catchments, not a national total
The research divides each city into practical drive-time catchments, then measures demand support, visible supply, development pipeline, rent evidence and property conversion conditions. A city can remain attractive while several local catchments are already over-supplied.
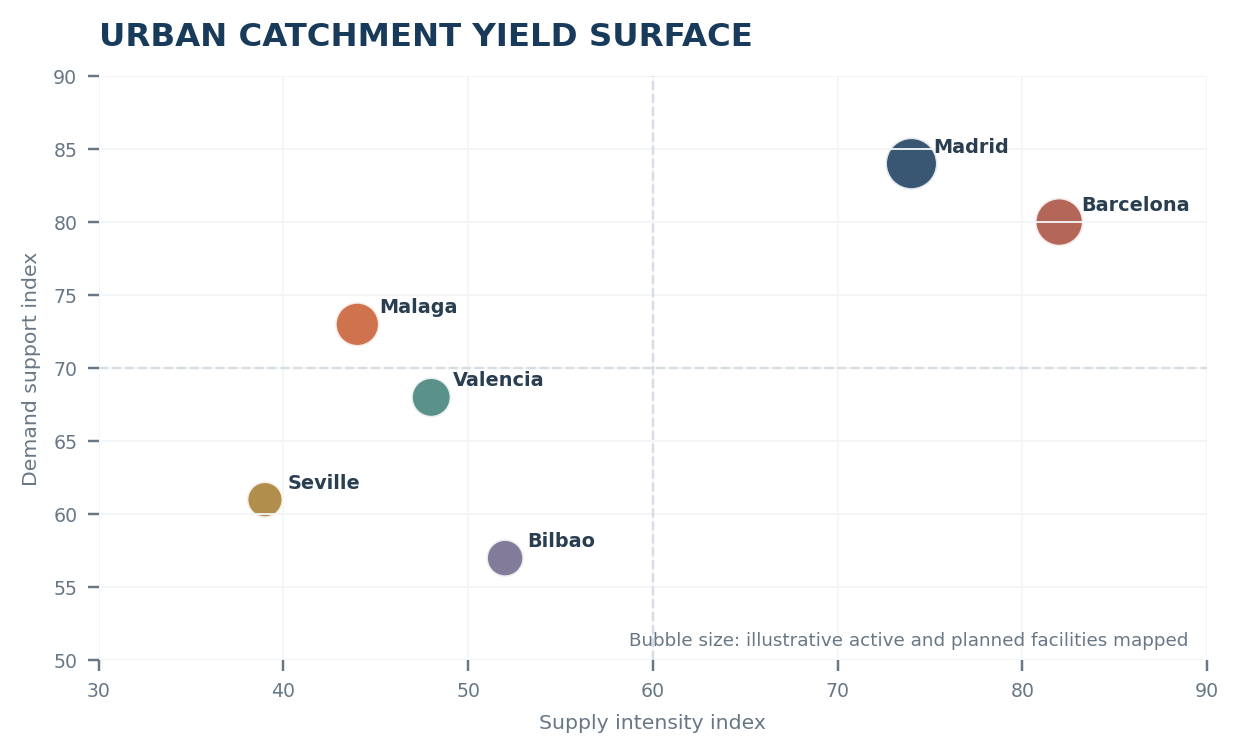
Catchment Yield Surface
SURFACE LAYER | EVIDENCE COMBINED |
|---|---|
Demand support | Household density, residential space pressure, renter mobility, small-business activity and digital search interest |
Supply reality | Operating facilities, rentable area, unit mix, pricing, reviews, opening dates and planned schemes |
Property fit | Access, visibility, loading, planning use, conversion capex, lease terms and alternative value |
Revenue evidence | Advertised and achieved rent, discount depth, occupancy ramp and ancillary income |
Potential inputs include AESS and FEDESSA market records, operator websites, planning portals, cadastral and property data, company accounts, mapping tools, review platforms and transaction databases.
ASSET AND OPERATOR SCREEN
Rebuild site economics before comparing acquisition prices
The research standardises units, rentable area, occupancy, discounting and property cost so that owned, leased and converted sites can be compared on a common basis. It also distinguishes mature cash generation from revenue that still depends on an assumed ramp.
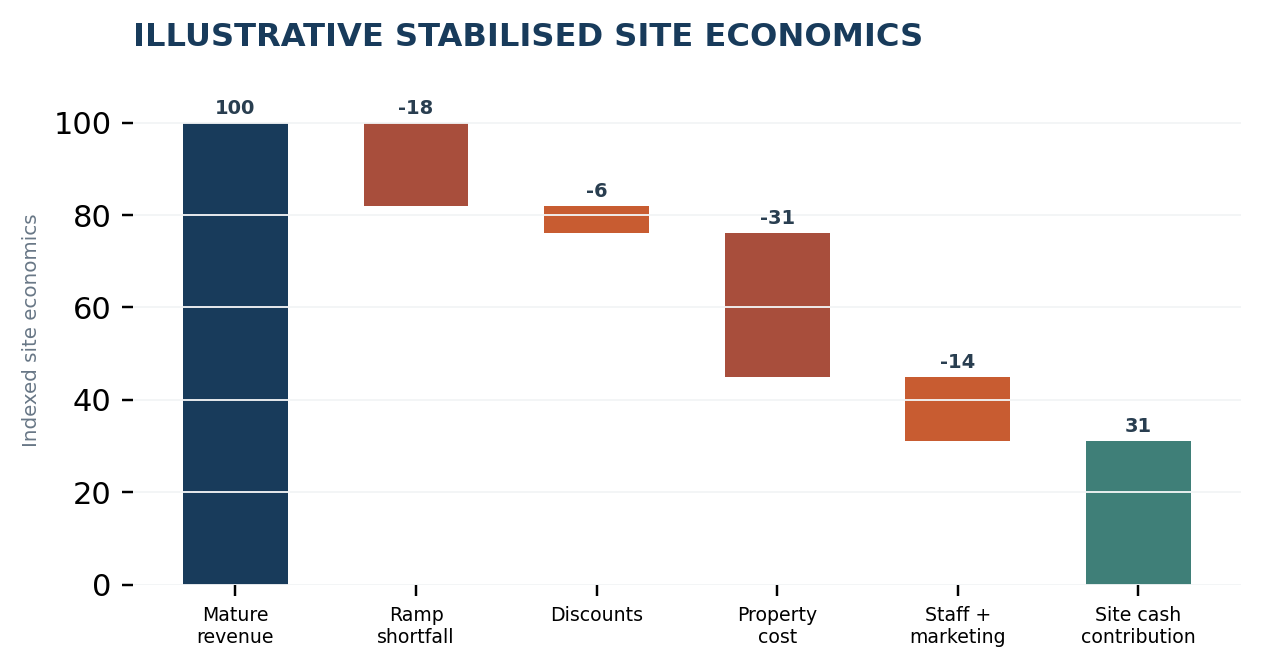
Illustrative screening result
UNIVERSE | DECISION MEANING |
|---|---|
94 facilities | mapped across the selected urban catchments |
27 operators | resolved to legal ownership and operating brand |
11 assets | advanced after property, access and economics filters |
6 assets | retained as acquisition or conversion candidates |
WHY THE FILTER MATTERS A low supply count is not enough. A facility advances only when local demand, property fit and a credible occupancy ramp support the same investment case.
STRESS TEST
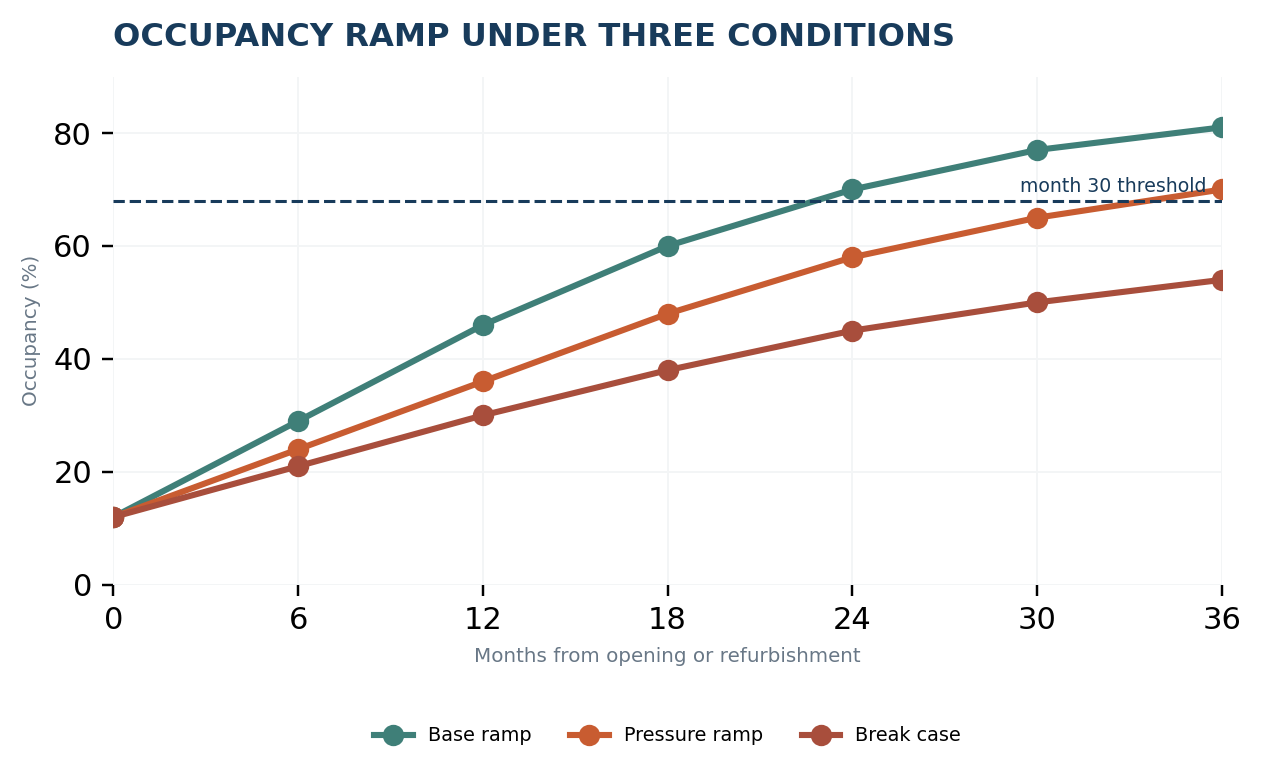
Occupancy timing carries more value than the headline rent
Self-storage economics are path-dependent. A delay in reaching stable occupancy increases marketing expense and property carry while reducing the time available to recover conversion capex. The stress model therefore changes the ramp itself, not only the terminal value.
VARIABLE | BASE CASE | PRESSURE | BREAKPOINT |
|---|---|---|---|
Month 30 occupancy | 77% | 65% | Below 60% |
Achieved annual rent | EUR 278/m2 | EUR 244/m2 | Below EUR 225/m2 |
Conversion cost | EUR 690/m2 | +17% | Above EUR 840/m2 |
Opening delay | 4 months | 8 months | More than 10 months |
Pipeline within catchment | 12% of current supply | 24% | Above 30% |
All facility counts and investment values are illustrative and scaled to the example mandate.
CAPITAL RESPONSE
Enter selectively through two urban clusters
The example supports a controlled entry in Valencia and Malaga, with Madrid used for selective acquisitions rather than broad development. Barcelona remains a monitor market because acquisition cost and pipeline pressure reduce the margin for error.
METRO | RESPONSE | INVESTMENT LOGIC |
|---|---|---|
Valencia | Advance | Balanced demand support, manageable visible supply and conversion candidates |
Malaga | Advance with conditions | Demand support is attractive; seasonality and property cost require tighter underwriting |
Madrid | Selective | Scale is available, but economics vary sharply by catchment |
Barcelona | Monitor | Higher supply and property pressure weaken the initial acquisition case |
Seville | Option value | Retain two candidates while testing rent and ramp evidence |
What the client receives
Facility census | Operator ownership map | Catchment yield surface | Asset comparability grid | Occupancy ramp model | Acquisition pipeline | Capital phasing conditions
DELIVERY A five-metro assessment can typically be delivered in six weeks. Timing varies with property evidence, ownership complexity and the number of acquisition candidates requiring reconstruction.
Note: The client, opportunity universe, financial assumptions, findings and conclusion are illustrative. They demonstrate the research approach and are not presented as an actual client outcome.
Contact Us
FIND THE CATCHMENTS THAT CAN SUPPORT CAPITAL Tell us the cities, asset route and operating assumptions under review. August Research will connect local demand, supply, property economics and ramp risk into one investment decision.